
Form 706 Filing Appraisals
Reports you can calculate from, file with confidence, and are written for review
The Filing Depends on Getting the Numbers Right
Gatsby Appraisal delivers independent, accurate, credible, and defensible date-of-death valuations supported by thorough market analysis and clear documentation.
Multiple Properties? Multiple Counties? Let's Talk.
An estate doesn't always fit neatly within one county—or one property type.
When an estate includes residential properties across Southern California, or a combination of residential and commercial real estate, coordinating multiple appraisals can become another responsibility in an already complicated process.
Gatsby Appraisal maintains professional relationships with fellow appraisers throughout Southern California, including a California Certified General Appraiser qualified to undertake commercial valuation assignments.
Whether your estate includes a family residence, rental properties, vacant residential land, or commercial real estate, we may be able to help you connect with the appropriate valuation professionals.
Send us your property list. We may be the only call you need to make.
When Do You Need an IRS Form 706 Real Estate Appraisal?
Sometimes, You Need the Value Before You Know Whether You Need the Filing.
Not every estate requires a federal estate tax return. But when real estate represents a substantial portion of an estate's assets, establishing its fair market value may be an important step in determining whether a filing is necessary.
An independent, well-supported appraisal can provide the documentation attorneys, CPAs, and estate representatives need in several circumstances.
When an Estate Is Approaching the Federal Filing Threshold
For individuals who die in 2026, the federal estate tax filing threshold is $15 million, calculated using the gross estate together with certain lifetime gifts. When substantial real estate holdings are involved, accurate valuations help the estate's advisors determine where the estate stands relative to that threshold.
When an Estate Contains Multiple Properties
A primary residence, vacation home, rental property, and vacant land may each require separate market analysis. The combined real estate holdings can represent a significant portion of the estate's total value, making consistent, well-documented valuations particularly important.
When a Surviving Spouse Is Considering Portability
An estate may elect to file Form 706 even when no federal estate tax is owed, preserving the deceased spouse's unused estate tax exclusion. Although simplified valuation reporting rules may apply to certain assets, independent appraisals can provide additional support when warranted by the property's characteristics or the estate's circumstances.
When a Property Requires More Than a Routine Valuation
Unusual homes, significant acreage, unpermitted improvements, substantial deferred maintenance, income-producing properties, and properties with limited comparable sales may require additional analysis to develop a credible opinion of fair market value.
Not Every Date-of-Death Appraisal Is for Form 706.
Some estates need a retrospective appraisal to establish inherited property values, support estate administration, or document a potential tax basis without filing a federal estate tax return.
Gatsby Appraisal provides both general date-of-death valuations and appraisals developed for federal estate tax reporting, with the scope and supporting analysis tailored to the assignment's intended use.
Not sure which appraisal you need? We're happy to discuss the valuation requirements with you and coordinate with your attorney or CPA.
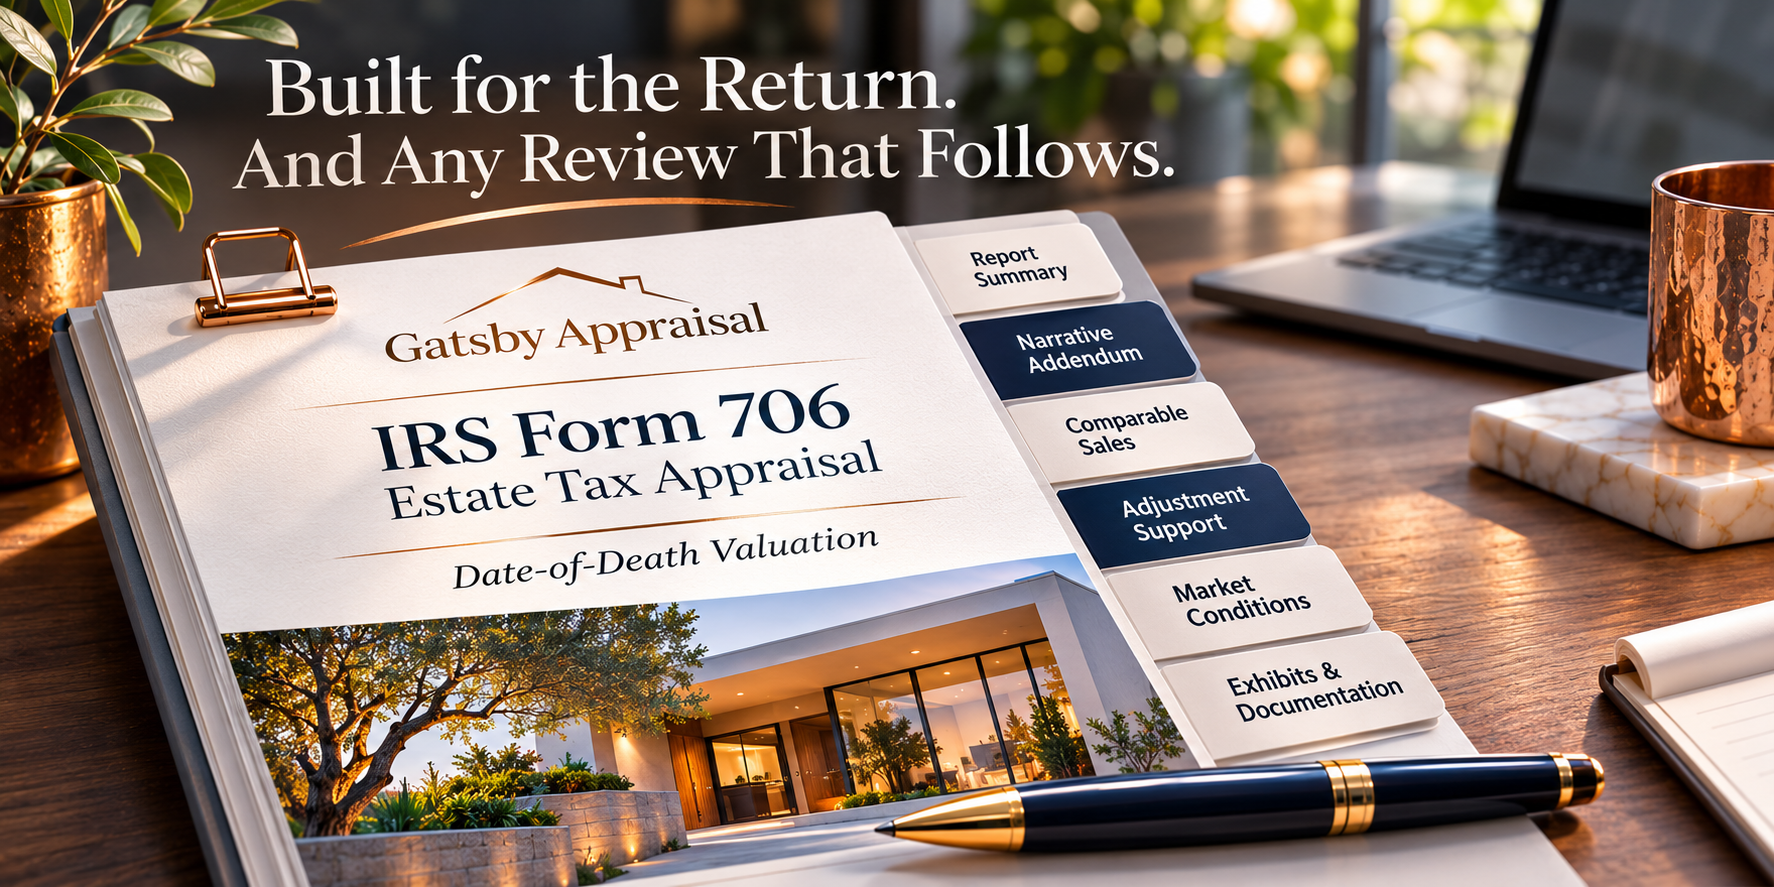
Built for the Return And Any Review That Follows.
An appraisal submitted with an IRS Form 706 estate tax return becomes part of the documentation supporting the estate's reported real estate values. It may be reviewed by the estate's CPA, attorney, executor, beneficiaries, or the IRS itself.
That is why we prepare our reports to explain not only what a property was worth, but why the market supports that conclusion.
Our valuations apply the federal estate tax definition of fair market value: the price at which a property would change hands between a willing buyer and willing seller, neither under compulsion and both reasonably informed of the relevant facts.
Whether the market evidence supports a higher or lower value, our responsibility remains the same: an independent, credible, and defensible conclusion—not a predetermined financial outcome.
We don't manufacture value to influence estate tax obligations. We document what the market supports.
The Right Property. The Right Market. The Right Date.
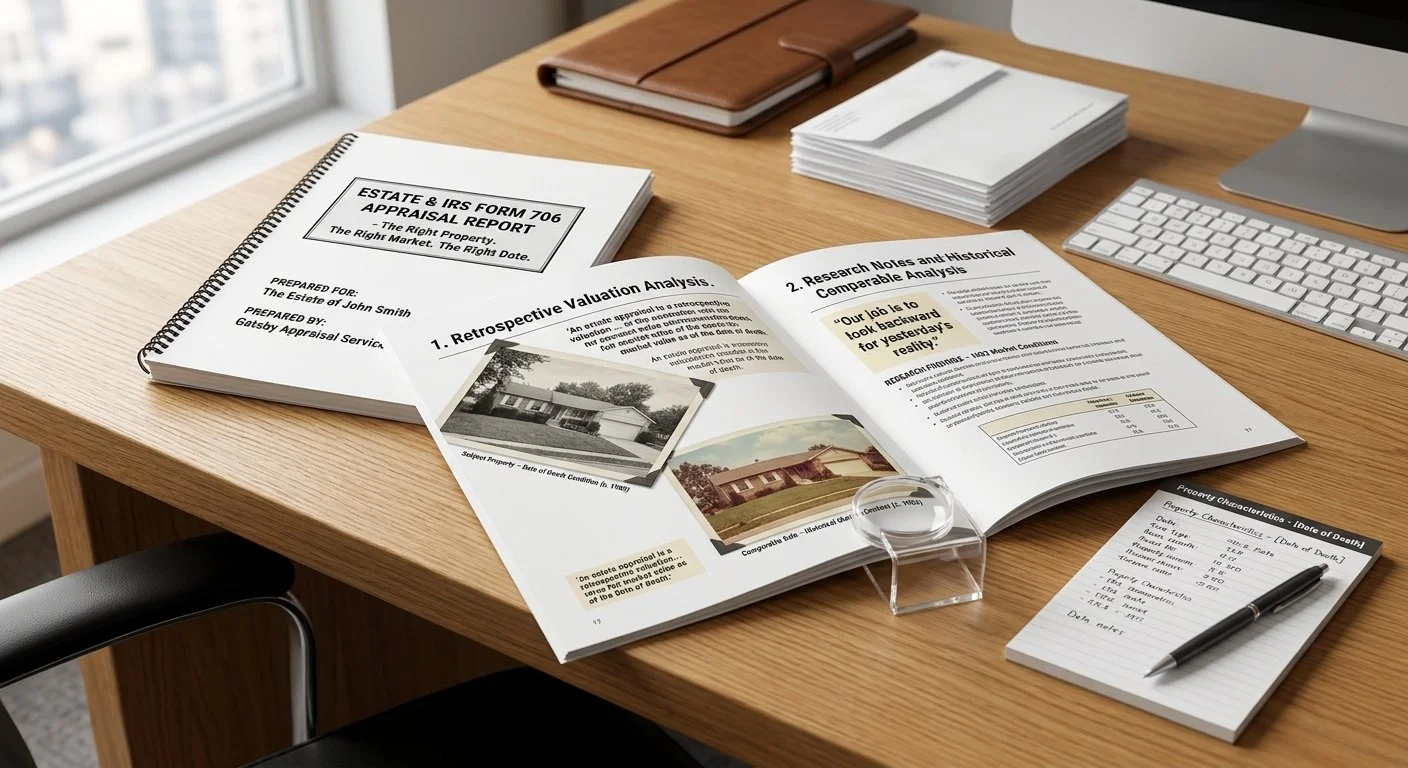
An estate appraisal is a retrospective valuation. It must consider the property as it existed and the market conditions prevailing on the applicable valuation date.
The residence may have since been emptied, remodeled, repaired, or sold. The surrounding market may have appreciated, declined, or experienced significant changes in buyer behavior.
Gatsby Appraisal researches historical sales, property characteristics, market conditions, and available documentation to develop a supported opinion of fair market value as of the date of death.
What About the Alternate Valuation Date?
Under certain circumstances, an estate may qualify to elect an alternate valuation date under Internal Revenue Code Section 2032, generally six months after death. Property sold or otherwise disposed of during that period may be subject to an earlier applicable valuation date.
We can provide additional retrospective valuations to assist the estate's tax professionals in evaluating the available options.
The decision to elect alternate valuation belongs to the estate and its tax advisors, subject to applicable IRS requirements.
“Our job is to look backward with the benefit of research—not to substitute today’s conditions for yesterday’s reality.”
The Value Matters Beyond the Filing.
Today's Estate Valuation May Affect Tomorrow's Tax Decisions.
An accurate real estate valuation can serve several important purposes beyond establishing the amount reported on Form 706.
Neither an unsupported low value nor an inflated conclusion serves the estate's long-term interests.
Our responsibility is to provide credible market evidence that can be relied upon when making these important decisions.
Estate Tax Calculations.
Real estate may represent a substantial portion of an estate's assets. Reliable market values help attorneys and CPAs evaluate the estate's total value and determine whether federal estate tax reporting requirements apply.
Inherited Property and Stepped-Up Basis.
Under applicable federal tax rules, inherited real estate generally receives a tax basis related to its fair market value at death or the applicable alternate valuation date. That basis may influence the capital gains calculation when beneficiaries eventually sell the property.
Portability Elections.
Some estates file Form 706 even when no federal estate tax is due, electing to preserve a deceased spouse's unused estate tax exclusion for the surviving spouse. Special valuation reporting rules may apply, making coordination with the estate's tax professionals particularly important.
Prepared for the Filing. Available for the Questions.
Because Good Documentation Shouldn't Require Guesswork.
Federal estate tax returns are generally due nine months after the date of death, although filing extensions may be available.
We understand that estate administration involves deadlines, multiple professionals, and sometimes several properties requiring independent valuation.
At Gatsby Appraisal, we discuss the assignment scope, documentation needs, and anticipated completion timeline at the outset so the estate's representatives can plan accordingly.
We also recognize that our work becomes part of a larger professional process.
We welcome appropriate communication with your estate attorney or CPA, including questions about comparable sales, market conditions, adjustments, and the reasoning supporting our conclusions.
Our reports are developed to communicate the analysis clearly, allowing the intended users to understand the market evidence behind the value opinion.
Independent research. Clear documentation. Conclusions supported by the market.
That's the foundation of every Gatsby estate valuation.